The Surcharge Paradox

Why 31% of Americans Call Credit Card Surcharges “Totally Unfair” – and 99% Pay Anyway
A national TRC study of 959 U.S. adults on point-of-sale credit card fees, payment substitution, and the gap between consumer outrage and consumer behavior.
Executive Summary
Surcharges are the 2 – 4% fee a merchant adds when a customer pays by credit card. Recently, surcharging has moved from a regional novelty to a mainstream checkout experience. It can be found everywhere from coffee shops, to restaurants, to online storefronts. For merchants, payment networks, and fintech providers, the central question is no longer whether consumers notice these fees, but how they react to them, and whether that reaction shows up at the register.
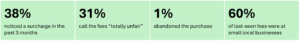
To answer this, TRC Insights surveyed N=959 U.S. adults in late 2025 about their payment habits and direct experiences with credit card surcharges. The findings reveal a sharp disconnect. Roughly 38% of consumers reported noticing a surcharge in the prior three months, and nearly one in three (31%) consider the fees “totally unfair.” Yet among shoppers who actually encountered a disclosed fee, 99% completed the purchase anyway, and 47% paid with the very credit card that triggered the charge.
Surcharges are off-putting, but the impact appears to be delayed and uneven. About 53% of fee-payers took some downstream action (most commonly deciding not to return to the business) and the form of resistance splits sharply by age: older consumers retreat to cash, while younger consumers pivot to mobile wallets and are far more likely to leave a negative review or dispute the charge. Because surcharges concentrate at restaurants, bars, and small local businesses, the reputational cost falls hardest on the merchants least able to absorb it. The strategic implication for businesses is that a 3% surcharge rarely results in a lost sale, but they quietly erode loyalty, and how the fee is disclosed determines how much damage is done.
Industry Context
Three forces have pushed surcharging into the mainstream. First, interchange economics: persistent inflation and thin post-pandemic margins have made the 1.5–3.5% that card networks (like Stripe and PayPal) charge merchants per transaction harder to swallow quietly. Industry reporting indicates that roughly a third of U.S. small businesses now add a credit card surcharge of some kind. Second, regulatory permission: surcharging is now legal in most U.S. states, with rules governing disclosure and caps rather than outright bans, giving merchants permission to pass costs through. Third, payment fragmentation: the rise of debit, mobile wallets, and Buy Now, Pay Later means consumers facing credit card fee have more payment alternatives than ever before.
This matters now because the surcharge sits at the intersection of pricing psychology and payment choice. A surcharge is not a price increase in the conventional sense – the shelf price is unchanged – but it is a visible, itemized penalty applied at the most sensitive moment in the transaction. Classic pricing research holds that consumers react more strongly to a fee framed as a surcharge than to an equivalent amount baked into the base price. The question for the payments ecosystem is whether that reaction is strong enough to change behavior, or whether convenience wins. Our data suggests the answer is more nuanced than either side of the debate assumes.
Methodology
TRC Insights fielded an online survey of N=959 U.S. adults (ages 18+) between November 17 and December 1, 2025. The sample was balanced and weighted to U.S. Census benchmarks for age, gender, and household income, so results are representative of the national adult population. At the total-sample level, results carry a margin of error of approximately ±3 percentage points at the 95% confidence level; subgroup estimates (for example, those who recalled a specific fee) rest on smaller bases and should be read as directional.
The survey instrument combined closed-ended payment-behavior questions with AI-moderated open-ended probes, allowing respondents to explain their reasoning in their own words. Subgroup differences reported here – by gender and by age band (18–34, 35–54, 55+) – were tested for statistical significance using two-tailed Z-tests at the 95% confidence level. Verbatim responses from the open-ends were also reviewed to surface the reasoning behind the numbers.
This study was designed to quantify how surcharges shape consumer behavior. Specifically, it set out to:
- Measure how often surcharges are noticed, and which consumers notice them most;
- Distinguish stated attitudes toward surcharges from actual behavior at the point of sale;
- Identify where surcharges are encountered – by spending category and business type;
- Map the payment-substitution patterns triggered by a fee, and how they differ by age and gender; and
- Assess how fee disclosure (clear versus hidden) affects consumer reaction and merchant reputation.
Key Findings
Finding 1: The attitude-behavior gap is enormous
Consumers dislike surcharges in principle but comply in practice. Asked to summarize their feelings, 31% called the fees “totally unfair” and said they would avoid merchants that charge them, another 31% disliked the fees but said they would not change their behavior, and 38% accepted them as a reasonable pass-through of card costs. When the moment of truth arrived, however, attitude collapsed into compliance: of those who encountered a clearly disclosed fee, 99% paid anyway – and 47% simply paid with their credit card despite the penalty.
“They typically won’t affect my spending because surcharges are normal…it was only 1 dollar so it’s fine.” Male, 18–24
This is a key insight: a surcharge almost never loses the immediate sale. Outright purchase abandonment was under 1% in the moment. The cost is not lost transactions – it is eroded goodwill that surfaces later.
Finding 2: Resistance is delayed, not absent
The compliance figure masks a slower-burning reaction. Among consumers who noticed a fee, 53% reported taking some follow-up action, most often deciding to stop spending money with that business (26%). Some people left a bad review (12%), complained to the owner (13%), or disputed the charge with their card issuer (12%). Basically, the fee is paid at the register and punished afterward – a pattern conventional point-of-sale conversion metrics would entirely miss.
Finding 3: How consumers resist splits sharply by age
When a fee prompts a change in payment method, the substitute chosen depends heavily on generation. Older consumers retreat to cash; younger consumers reach for a phone. Although some mobile wallet options still ultimately use a CC and carry a surcharge.
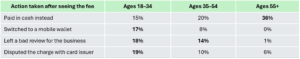
Weighted percentages among respondents who encountered a disclosed surcharge. Differences shown are significant at the 95% confidence level.
Awareness follows the same generational gradient: 49% of 18–34s noticed a fee in the past three months versus 29% of those 55+. And while younger consumers are more attuned to the fee, older consumers are the most morally opposed to it – 43% of those 55+ call surcharges “totally unfair,” against just 15% of 18–34s. The older group objects loudest and votes with cash; the younger cohort shrugs, taps a wallet, and posts a review.
Finding 4: The fee lands hardest on small, local merchants
Surcharges are not evenly distributed across the economy. The single most common place consumers last saw a fee was restaurants, bars, and cafes (28%), and when asked about the type of business, 60% identified a small local business rather than a national chain. This dynamic creates an interesting situation: the merchants most likely to surcharge – independent operators with the thinnest margins – are also the ones most exposed to the delayed reputational penalties, where a lost regular or a one-star review carries disproportionate weight.
“I understand why they are being applied, however, I think they are awful…but small businesses cannot absorb any more charges.” Female, 55–64
Finding 5: Consumers forgive the small business and escalate against the chain
Consumers who last saw a surcharge at a small local business were markedly more forgiving than those who saw one at a national or regional chain. Among small-business fee-payers, 60% took no follow-up action at all, versus 40% at chains. The gap is sharpest in the confrontational responses: chain customers were roughly four times as likely to complain to the manager (25% vs. 6%) and three times as likely to dispute the charge with their card issuer (18% vs. 6%) – both differences significant at the 95% confidence level. The instinct to escalate is reserved for the faceless brand, while the local operator often gets a pass from the buyer.
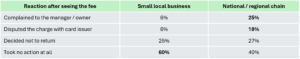
Weighted percentages among respondents who encountered a surcharge and identified the business type. Small local business n=110; national/regional chain n=68. Differences shown are significant at the 95% confidence level.
The one reaction that does not differ by business type is the quiet decision not to return (25% small business vs. 27% chain). The silent-attrition risk is roughly constant across merchant types – it is the loud, public forms of retaliation (complaints, disputes, reviews) that consumers withhold from the small operator. The local business is spared the confrontation, not the churn.
“I understand small businesses add them; never had a large company add a fee. I try to use cash or check if I know there will be an added fee.” Female, 45–54
Finding 6: Disclosure is the single biggest lever merchants control
How the fee is communicated shapes the reaction. Encouragingly, 81% of consumers said the surcharge was disclosed before they paid – typically when they received their total. But the remaining ~19% who discovered the fee only on a receipt or statement skewed older and reacted far more negatively. Among consumers 55+, nearly one in three encountered a fee that was not clearly disclosed in advance, and undisclosed fees were strongly associated with the “never shop here again” response. The verbatims make the emotional logic plain.
“I feel like I’m being double charged…I’m being asked to pay extra for using a card that helps them get paid sooner.” Female, 55–64
Strategic Implications
For merchants, the data reframes the risk. The threat of surcharging is not cart abandonment, it is silent attrition. Because 99% proceed with the purchase and only a minority complain on the spot, conversion dashboards will show the fee “working,” even as a quarter of customers privately decide not to return. Independent restaurants and local retailers, the heaviest surchargers, are precisely the businesses whose economics depend on repeat visits, and just a few negative online reviews can have a monster impact. So, the long-run trade between fee revenue and lifetime value deserves explicit modeling rather than assumption. The attrition risk is the part small merchants cannot dodge: customers spare the local operator the public complaint or dispute they would aim at a chain, but the quiet “won’t be back” decision runs at roughly the same rate (about a quarter) regardless of business type. Goodwill buys the small business a softer confrontation, not immunity from lost repeat visits.
For companies, the age-based substitution pattern is a roadmap. Every surcharge is a moment of payment reconsideration, and the winners differ by generation. Mobile-wallet providers have a clear opening with consumers under 35, who actively pivot to wallets to dodge card fees; debit rails and cash-back debit products are better positioned for older, fee-averse shoppers.
For anyone setting communication strategy, disclosure is the highest-leverage variable. The same fee generates acceptance when surfaced before payment and resentment when discovered afterward. Transparent, up-front disclosure is not merely a compliance checkbox – it is the difference between a customer who grumbles and pays and one who pays, leaves, and tells others why.
Recommendations
- Disclose the fee before the total, not after. The 19% who learn of a fee late are the ones who churn. Surface the surcharge at the point a total is presented, in plain language, to convert resentment into reluctant acceptance.
- Model lifetime value, not just transaction margin. With roughly a quarter of fee-payers deciding not to return, merchants should weigh recovered interchange against the cost of lost repeat business – especially in food service and local retail.
- Segment payment strategy by age. Offer fee-free debit or cash incentives to older customers and frictionless mobile-wallet acceptance to younger ones; the same surcharge pushes the two groups toward different alternatives.
- Monitor reviews and disputes as leading indicators. Because resistance is delayed, online reviews and chargeback rates – not checkout conversion – are the early-warning signals that a surcharge is damaging the relationship.
- Test the framing before rolling it out. Pricing research can quantify the goodwill cost of a surcharge versus a built-in price or a cash discount before a business commits to a policy that is hard to reverse.
Conclusion
Credit card surcharges are not going away. As fielded in late 2025, this research shows consumers have already absorbed them into routine behavior: they notice, they object, and they still pay. The mistake businesses can make is reading that compliance as acceptance. The real story sits in the gap between the 31% who call these fees unfair and the 99% who continue with the purchase, a gap that resolves not at the register but weeks later, in a customer who quietly takes their business elsewhere. The surcharge rarely loses the sale. Managed carelessly, it loses the customer.
Author Credentials
Ted Benzing is Vice President at TRC Insights and has spent more than 20 years helping brands make smarter, more confident decisions through marketing research, with a particular focus on pricing strategy. Across a wide range of industries, he has helped clients answer one of the hardest questions in business: “What should we charge?”, using methods that range from straightforward price-sensitivity testing to advanced choice modeling. He earned his MBA in Marketing Insights and Analytics from the University of Wisconsin–Madison, home of the A.C. Nielsen Center for Marketing Analytics and Insights, and holds a BBA in Accounting from the University of Iowa’s Tippie College of Business.
Ted writes regularly on pricing and payments for the TRC blog and can be reached at tbenzing@trcinsights.com.
References & Data Sources
- TRC Insights, “Digital Twins / FinTech Payment Survey” (study j17268), national online survey of 959 U.S. adults, fielded November 17–December 1, 2025; weighted to U.S. Census age, gender, and income benchmarks. Primary data source for all statistics in this paper. https://merchantcostconsulting.com/lower-credit-card-processing-fees/credit-card-surcharge-laws-by-state/
- Third of U.S. small businesses add credit card surcharges | Payments Dive https://newsroom.wise.com/en-NAM/233952-widespread-consequences-of-junk-fees-uncovered-with-financial-transactions-showing-most-impact-on-americans/
- In re Payment Card Interchange Fee and Merchant Discount Antitrust, No. 12-4671 (2d Cir. 2016) https://law.justia.com/cases/federal/appellate-courts/ca2/12-4671/12-4671-2016-06-30.html